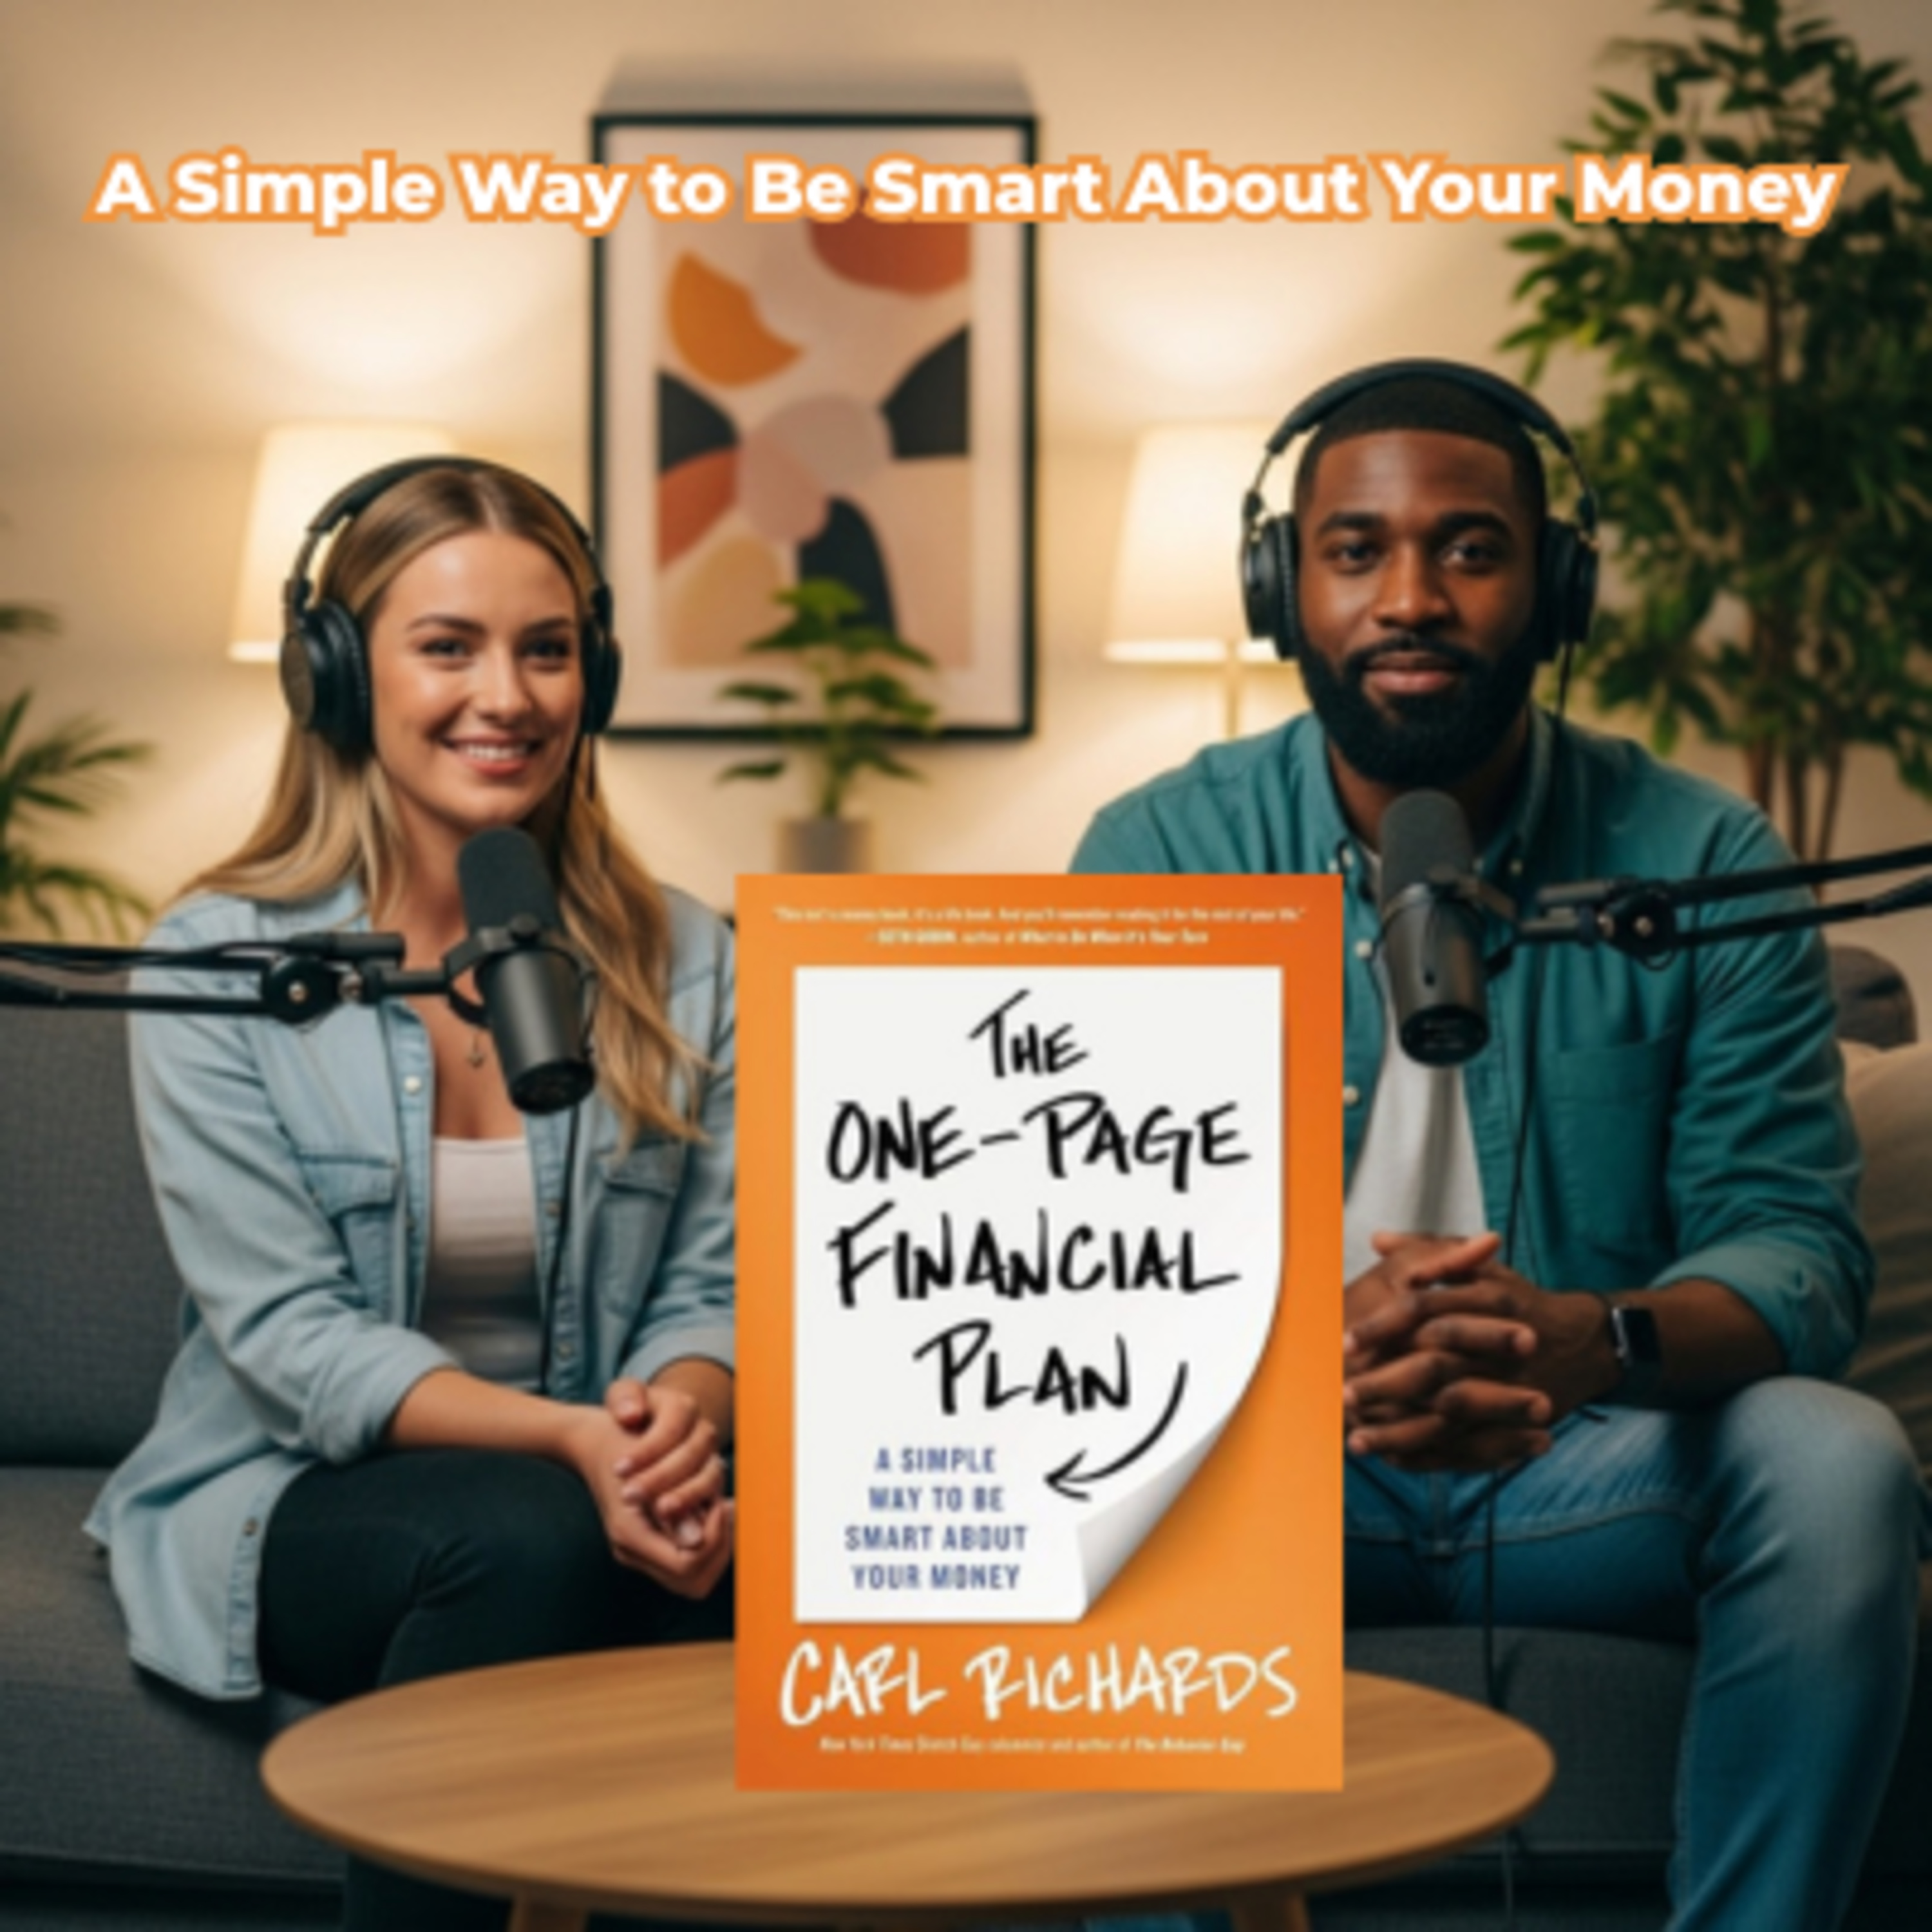
The One-Page Financial Plan by Carl Richards
Whenever I tell people about my job as a financial advisor, the conversation inevitably turns to how hopeless they feel when it comes to dealing with money. More than once, they’ve begged, “Just tell me what to do.”
It’s no surprise that even my most successful friends feel confused or paralyzed. Even if they have a shelfful of personal finance books, they don’t have time to make sense of all the information available. They don’t just want good advice, they want the best advice—so rather than do the “wrong thing,” they do nothing. Their 401(k) and bank statements pile up, unexamined or maybe even unopened.
What they don’t realize is that bad calls about money aren’t failures; they’re just what happens when emotional creatures have to make decisions about the future with limited information. What I tell them is that we need to scrap striving for perfection and instead commit to a process of guessing and making adjustments when things go off track. Of course we’re going to make the best guesses we can—but we’re not going to obsess over getting them exactly right.
The fact is, in a single page you can prioritize what you really want in life and figure out how to get there. That’s because a great financial plan has nothing to do with what the markets are doing, what your real estate agent is pitching, or the hot stock your brother-in-law told you about. It has everything to do with what’s most important to you.
By now you may be wondering, “What about the details? How much do I need to invest each year, and how do I allocate it? How much life insurance do I need?” Don’t worry: I’ll cover those topics and many more, sharing strategies that will take the complexity out of them.
The most important thing is getting clarity about the big picture so you can cope with the unexpected. Maybe you’ll lose the job you thought was secure; you’ll take a financial risk that doesn’t pan out; you’ll have twins when you were only budgeting for one. In other words: Life will happen.
But no matter what happens, this book will help you bridge the gap between where you are now and where you want to go.
This episode outlines a simplified methodology for achieving financial independence by focusing on personal values rather than complex spreadsheets. The author suggests that a single-page plan reduces stress by aligning specific monetary goals with what an individual truly prizes, such as family or travel. Key strategies include tracking expenses to build awareness, automating savings to ensure consistency, and maintaining a long-term investment perspective. By avoiding reactionary changes to market fluctuations, individuals can harness the power of compound growth over time. Ultimately, the source advocates for a minimalist approach to money management that emphasizes clarity, discipline, and purpose. #TheOnePageFinancialPlan #CarlRichards #PersonalFinance #productivityhacks #personaldevelopment #successstrategies #businessinsights #leadershipskills #leadership #ambitiousprofessionals #businesstips #self help #scaling business #businesstactics #professionaldevelopment #startupgrowth #entrepreneurship #businessmindset #growthstrategies
Have you ever, like, sat down to look at your bank accounts? You know, determined to finally get things in order. Oh, and you just immediately feel that wave of absolute exhaustion hit you. Exactly like you're staring at a puzzle that's missing half its pieces, right? And the pieces you actually do have are written in a foreign language. Yeah, it's an incredibly common feeling. Honestly, it would be weird if you didn't feel overwhelmed by it all. Right, because they're all these, you know, confusing tax laws and dense investment guidelines everywhere.
Oh, and 50 different types of retirement accounts. Exactly. And these incredibly intricate investing tactics just screaming at you from every corner of the Internet. It really feels like you need a pH. D in advanced economics just to figure out how to like, pay for your groceries, keep the lights on, and maybe, just maybe save a few dollars for the future. Which is just exhausting. It is, but today our mission for this deep dive is to completely cut through all of that paralyzing complexity. We are going to toss out the stressful spreadsheets.
Yes, please. Right, we're tossing the heavy workload, and instead we're discovering A simplified, surprisingly intuitive shortcut to financial stability. And we're using some brilliant concepts today to guide us. We're exploring the core philosophy from Richard's book, The One Page Financial Plan. Such a great. Book it really is. And the underlying argument here is that the secret to reaching your goals isn't, you know, adding more complex strategies to your life. It's actually about stepping back, stripping away the excess and just ignoring the noise.
OK, let's unpack this because when I first started looking at these concepts, the whole thing really struck me as building a personal financial GPS for yourself. Oh, I like that. Yeah, like if you're trying to drive across the country, you don't need to memorize every single back Rd. and detour in existence, right? Right. Of course not. You just need to know where you currently are, where you want to end up, and the simplest route to get there. Yes, and the GPS analogy perfectly captures the spirit of what we're doing today.
We're really looking for the why behind your numbers rather than just doing complex math for the sake of it. Because the math alone doesn't really mean anything. Exactly, because if you don't understand the why, the math itself is completely meaningless. I mean, you can run the most sophisticated algorithms in the world to optimize your income, but if that optimized income doesn't align with the life you actually want to live, what's the point? It's useless. Completely useless. Which brings us right to the starting line, or as Richards describes it, the crossroads.
Think about it. You can't program a GPS if you don't actually type in a destination. So before you look at a single number, before you open Excel, and definitely before you download yet another budgeting. App. Well, the ones that just send you push notifications to make you feel guilty. Yes, there's exactly. Before you do any of that, you absolutely must begin by identifying your core values. And this is where people usually get tripped up because it sounds almost, I don't know, too philosophical for a finance discussion.
Yeah, like we're doing therapy instead of math. Exactly. But pick yourself standing at a literal crossroads. Stretching out in front of you are a dozen different paths. One path is buying a house, another is traveling the world, another is retiring early. Paying for your kids college, right? How on earth do you choose knowing your core beliefs? What actually matters to you deep down is the only reliable way to make the proper decision. That is the fundamental role of values in this framework. It's your compass.
And the practical starting point here is refreshingly low tech. You just need to sit down and write your top three values on a piece of paper. Just three. Just three. And once you have those core beliefs staring back at you, then you set precise financial objectives that correspond directly to them. And the beauty of this approach is in the clarity it brings. Like, let's walk through how this actually works. Say you write down that one of your core values is exploration and adventure. A great value to have.
It's a wonderful value, but it's abstract. A bank teller doesn't know what to do with adventure, so the next step is translating that abstract value into a tangible numerical objective. So if you value exploration, your financial goal becomes accumulating enough money to actually go do it. Like setting aside a specific amount for a trip, say, deciding to save $200 every single month so that you know a year from now you can take your family to Europe to create those lifelong experiences. You aren't just saving money in a vacuum anymore.
You're not just hoarding cash because some financial guru on TV told you to. Your money suddenly has a very real, very personal sense of purpose. Which is exactly what keeps you motivated. But hold on, let me play devil's advocate for a second. Here is a budget based on values, just like a glorified wish list. How so? Well. If my top value is adventure, how does writing that word down on a notepad actually fix my messy finances? Doesn't that just encourage me to go out and buy plane tickets I can't actually afford because, hey, it's my value?
What's fascinating here is that defining your values isn't about ignoring your financial reality, and it's definitely not giving yourself a blank check. It's actually the exact opposite. It's about creating an incredibly strict filter for your decisions. When you clearly define that trip to Europe as your ultimate priority, it naturally forces you to evaluate every other purchase against that specific goal. Oh, I see. Yeah, you aren't saving for the sake of saving, which usually just feels like deprivation and misery.
You're reallocating your limited resources toward what is genuinely worthwhile to you. So by identifying the value, you're actually giving yourself permission to say no to the things that don't matter. That's nicely. Because you're saying a big enthusiastic yes to the things that do. I mean, it's much easier to walk past a pair of expensive shoes when you realize those shoes are actively stealing a day in room from you. You've nailed it. You're standing at that crossroads. Every time you open your wallet and your defined value points you down the correct path, it just completely removes the decision fatigue.
OK, so we've got our destination programmed into the GPS. We know our core values and we've translated them into goals. But how do we map out those goals without slipping right back into those confusing multi step formulas that make personal finance so incredibly stressful in the first place? The answer here is a severe, almost radical constraint. You keep your entire financial plan to a single piece of paper. Literally just one page. Just one page. So no appendices, no 40 tab spreadsheets. Nope.
Think about the difference between trying to execute an intricate, highly technical recipe from a Michelin star chef versus throwing together a simple, straightforward family recipe you know by heart. Oh yeah, 1 is definitely more prone to disaster. Exactly. Attempting to adhere to an intricate financial formula is confusing, it's exhausting, and it's highly prone to error. You miss one step and the whole souffle collapses, right? But a simple one page plan? It forcefully eliminates the unnecessary elements and concentrates your attention only on the things you can control.
So the practical take away here is to grab a physical sheet of paper. You write down those core beliefs and objectives we just talked about, and you map out a clear, simple route to get there. You actively avoid juggling a bunch of competing complex plans. Yes, and the ichological benefit of this radical simplification is just huge. It makes it significantly easier to stay the course when life gets chaotic. Which it always does. Always. Let's look at retirements an example. People often get completely bogged down in intricate investing schemes when they plan for retirement.
They think they need complex derivatives or they need to be constantly shifting their asset allocations based on like what the Federal Reserve did on Tuesday. Right, They think they need to be glued to a Bloomberg Terminal with three monitors just to be allowed to retire at 65. Exactly. But on a one page plan, that retirement strategy cuts through all that noise. It can simply read, save $500 per month, invest in a diversified index fund and review it once a year. That's the entire plan. Save 500 month.
Diversify. Look at it annually. Done. Done. By stripping away the noise, you eliminate the feeling of being overwhelmed. When the plan is that simple, you know exactly what to do today, tomorrow, and next month. Here's where it gets really interesting to me. I like to think of this one page plan as your financial emergency index card. OK, tell me more. Like if your house is suddenly on fire, you don't go looking for the original architectural blueprints to find the exit, you just run out the front door, right?
In the case of personal finance, if the stock market is suddenly crashing and the news anchors are all panicking and screaming about a recession. That's constantly. Right. You do not want to be digging through a dense 400 page textbook on economic theory to figure out your next move. You just want to look at your simple one page summary to remind you of your actual goal. It grounds you. That's a perfect way to look at it. It's a lifeline. Financial decisions become so much less intimidating when you have that single piece of paper to go back to.
It serves as a physical reminder of what you're actually trying to achieve, which is the absolute best defense we have against making reactive, fear based decisions when things get scary. All right, so we have our values and we have our one page map holding everything together. But let's be honest, a map is completely useless if you're driving down the highway totally blind, right? You need to know how fast you're moving, how much gas is in the tank, and whether or not you're slowly veering off the road into a ditch.
Which brings us to the day-to-day mechanics. We need a speedometer. We're talking about tracking your money. Yes, trying to navigate your finances without tracking your expenses is exactly like driving a vehicle without a speedometer. Terrifying. If you have no mechanism to measure your speed, how would you possibly know if you were moving too quickly? You wouldn't know until you got pulled over or crashed. By tracking your spending, you finally see clearly where your money is actually flowing. And then you can use that empirical data to make wise decisions exactly to build the speedometer.
The suggestion here is to monitor your earnings and your outlays meticulously, but just for one single month. Right, just 30 days. You track absolutely everything, the rent, the groceries, right down to that $3 morning coffee you buy on the way to work. Or that random subscription you forgot to cancel. Oh, always the subscriptions. And you do this not to punish yourself, but to spot trends and identify the leaks in the boat. It's an exercise in pure data collection. I mean, it can be a little painful to look at, but it's incredibly illuminating.
Let's look at how this plays out in reality. Suppose that after tracking every penny for 30 days, you realize you're spending $400.00 a month on random take away food and delivery apps. Ouch, right? It's a massive trend you probably wouldn't have noticed without the speedometer, because it happens 20 or 30 bucks at a time. So armed with that data, you decide to cook at home more often. And the ripple effects of that one seemingly small decision are huge. Not only do you stop bleeding cash on delivery fees, but maybe you discover you actually enjoy cooking, you eat a bit healthier, and you get to spend better time with your family in the.
Kitchen. Yeah, exactly. And crucially, you can then take those funds rescued from the take away apps and redirect them straight into that Europe trip fund we talked about earlier. Yes, it feeds right back into the goal. But let me pause here because I know what people are thinking. Budgeting usually feels like a straight jacket. Oh, absolutely. It feels like a rigid, miserable list of things you aren't allowed to do anymore. Like no more lattes, no more take out, sit in the dark and save. How do we actually shift our mindset so that tracking every penny for a month feels like a tool for freedom rather than a punishment?
It's a very valid concern, and honestly, that feeling of restriction is exactly why so many people abandoned budgets after two weeks. But the mindset shift comes from understanding the true purpose of the exercise. This isn't about restriction, it's about awareness. Awareness. Right. And awareness gives you immense strength. When you know precisely how much you spend and where it goes, you gain the power to make deliberate decisions rather than impulsive ones. Moving from impulsive to deliberate.
Exactly. If you know you desperately want to take your family to Europe, the decision to reduce eating out is no longer a punishment imposed on you by a spreadsheet. It's a conscious, empowering choice to prioritize your ultimate value over a fleeting convenience. Wow. Yeah, suddenly the budget isn't the enemy, it's the exact tool that is facilitating your freedom to travel. I love that framing the budget isn't telling you no, it's just asking you a question. Like, is this quick takeout burger more important to you than walking around Rome?
Right. And if the answer is no, then you happily skip the burger. OK, so we're checking our speedometer. We're finding this extra money by cutting out the friction that doesn't align with our values. Now how do we make sure those rescued funds actually reach our gold instead of just magically getting absorbed by some other random expense? Well, that requires building an engine. You can't rely on willpower alone, you have to automate the process. There's a really evocative analogy for this, comparing saving money to tending a garden.
If you want beautiful flowers to bloom in the spring, you can't just plant the seeds and hope it happens to rain often enough. No, you'd end up with a yard full of dirt. Right, You have to actively water the garden regularly, and the exact same logic applies to your financial future. If you make saving a consistent priority and tend to it regularly, it will grow and flourish. If you don't, it'll dry up. And the absolute best way to tend that financial garden is by taking the human element out of it.
The temptation to spend it. Right, The temptation to forget, temptation to spend the money elsewhere, the whole I'll do it next month mentality. You take that completely out of the equation. First you decide on a precise savings target. As we mentioned, this could be your retirement fund, the trip to Europe or just building an emergency. Reserve right? You need a specific bucket to fill. Next, you program a direct transfer to be made each and every payday from your checking account straight into that specific savings or investment account.
You automate it. By doing this, you are effectively paying yourself first before you even have a chance to do any discretionary spending. So using our earlier example, you log into your bank and set up an automated $200 per month transfer for that future trip. Yes, because it's fully automated and happens the day your paycheck hits. You scarcely even notice the money leaving your trucking account. You just adapt to living on the slightly smaller amount. Exactly. But after a year of this silent automatic watering of your garden in the background, you look up and you have $2400 sitting there.
You can go schedule that dream vacation and be completely stress free about paying for it. Feels like magic, but it's just automation. Hold on though, let me throw a logistical curveball at you. If I set up an automatic transfer to drain money into savings, the absolute second get paid. Aren't I risking not having enough leftover and checking for my actual bills like the rent, the electricity, the car payment? How do I automate this, set it and forget it garden without accidentally starving my checking account and bouncing checks?
That is a crucial point and it's where we have to connect this automation step directly back to the speedometer we just built in previous section. You aren't just guessing a number and automating blindly because you have already taken the time to track every single outlay for a full month. You have the hard data. You know exactly what your basic living expenses are. You know your baseline. Right, we did the homework. We already know our speed limit. Exactly because you have that acute awareness, you know exactly what amount is actually safe to automate.
You aren't guessing, it's a calculated move. That makes sense. And when you automate that safe amount, you start building a safety net. Knowing you have those funds quietly accumulating in the background means you're building a buffer for whatever life throws at you. It dramatically eases the daily tension we all carry regarding unexpected costs. It's all connected. The map tells you where to go, the speedometer gives you the data on how you're driving, and that data lets you safely build the engine of automation.
Perfectly summarized. OK. So we've captured the excess money. We're automating our saving for those short term goals and our emergency funds, but for the really major life changing goals like that 500 a month retirement plan on our one page map, the money actually needs to multiply. Yes it does. Saving cash under a mattress isn't enough because of inflation that requires the final and perhaps most difficult ingredient, time. We've reached the destination phase of the journey. This requires immense patience and a focus on long term investing rather than short term trading.
I understand this. Imagine planting a tree. OK, a tree, not a flower garden this time. Correct, because a tree is a multi decade commitment. When you plant a sapling you would never expect it to be a towering oak providing shade by next Tuesday. Obviously not. It's biologically impossible. It requires patience, care, and significant time to mature and yield food. Investing in the market is exactly the same mechanism. Your investments must be allowed to develop over a long horizon. So to apply this today, the move is to select investments that support those long term goals, like broad index funds for retirement.
And then, crucially, you have to resist the urge to review your accounts or adjust your assets based on whatever the stock market did today. You have to maintain your perspective and ignore the transient fluctuations of the news cycle. And this is undeniably the hardest part for most people. Human beings are biologically wired to react to immediate threats. When the market dips and there's a lot of red on the screen, our instinct is to pull the money out to save it. Like running from a predator.
Right play response. Exactly. But patience is mathematically necessary. Let's assume you invest $100 a month into a diverse stock portfolio. OK, $100 a month. Even if the market takes a dive next month, you don't panic, you don't sell, you just continue to invest that $100 regularly because over the long term, the mechanics of compound returns mean that your money will increase substantially. It builds on itself. Over a period of 10/20 or 30 years, that consistent, patient investing harnesses the sheer power of compound interest to bring you steadily closer to your retirement goal.
Investing for the long term is what allows you to comfortably ride out those terrifying short term market drops. So what does this all mean if we build on that tree analogy? Constantly checking daily stock prices, logging into your brokerage app on your phone every afternoon and tweaking your portfolio based on whatever a pundit said on TV today. It's exhausting just hearing it it. Is it's basically like planting A delicate little sapling in your yard and then digging it up every single weekend just to check and see if the roots are growing yet?
Yes. And what happens when you do that? You completely traumatize the root system. Yeah, you aren't helping it grow. You are actively killing the tree with your anxiety. It's so absurd when you picture it that way, but that is exactly what what we do with our retirement accounts. By turning off the financial news and not being dependent on daily stock prices, you allow the roots of your investments to actually take hold. And as a wonderful side effect, you significantly reduce your own daily stress levels.
It's a remarkable synthesis of financial strategy and human psychology. To summarize the journey we've taken today. Achieving financial success is not about deploying incredibly complex strategies. It's not about time consuming, back breaking calculations or outsmarting Wall Street. It all comes down to a few fundamental, repeatable steps. First, identifying your true core priorities. Second, making reasonable, clear goals and physically sitting them onto a single page. 3rd tracking your movements with a budget so you actually have the data.
4th automating your savings so you effortlessly pay yourself 1st. And finally acting consistently over long term without panicking when the wind blows. It really takes the fear out of the whole process, doesn't it? It takes this massive, looming monster of personal finance that we all dread and shrinks it down into a simple, incredibly manageable set of daily habits. It really does. If we connect this to the bigger picture, it becomes clear that personal finance is not an end unto itself. You aren't trying to win a high score in some giant economic video game.
Personal finance is ultimately just a tool. It's a mechanism designed to protect your time, facilitate the values you hold dear, and ultimately safeguard your Peace of Mind. That is such a powerful perspective shift. We have covered a lot of ground today, but I want to leave you with a final thought to ponder as you go about your week. It's something that builds directly on this idea of our values being the true driver of our finances. Go for it if personal finance is really just a mirror reflected what we care about, what does your current bank statement say your top value is right now?
If a complete stranger were to look at every single one of your outlays for the last 30 days, would they see the life you actually want to live, or would they just see a list of automated, unthinking habits you've accidentally fallen into? Yeah, it's a great question to end on. Thank you so much for joining us on this deep dive. We'll catch you next time.
 Apple Podcasts
 Castbox
 Castro
 Goodpods
 Moon FM
 Overcast
 Pocket Casts
 Podbean
 Podcast Addict
 Podcast Republic
 Spotify