Learn to Manage Your Money & Protect Your Financial Future | The Investment Answer by Gordon Murray and Daniel C. Goldie
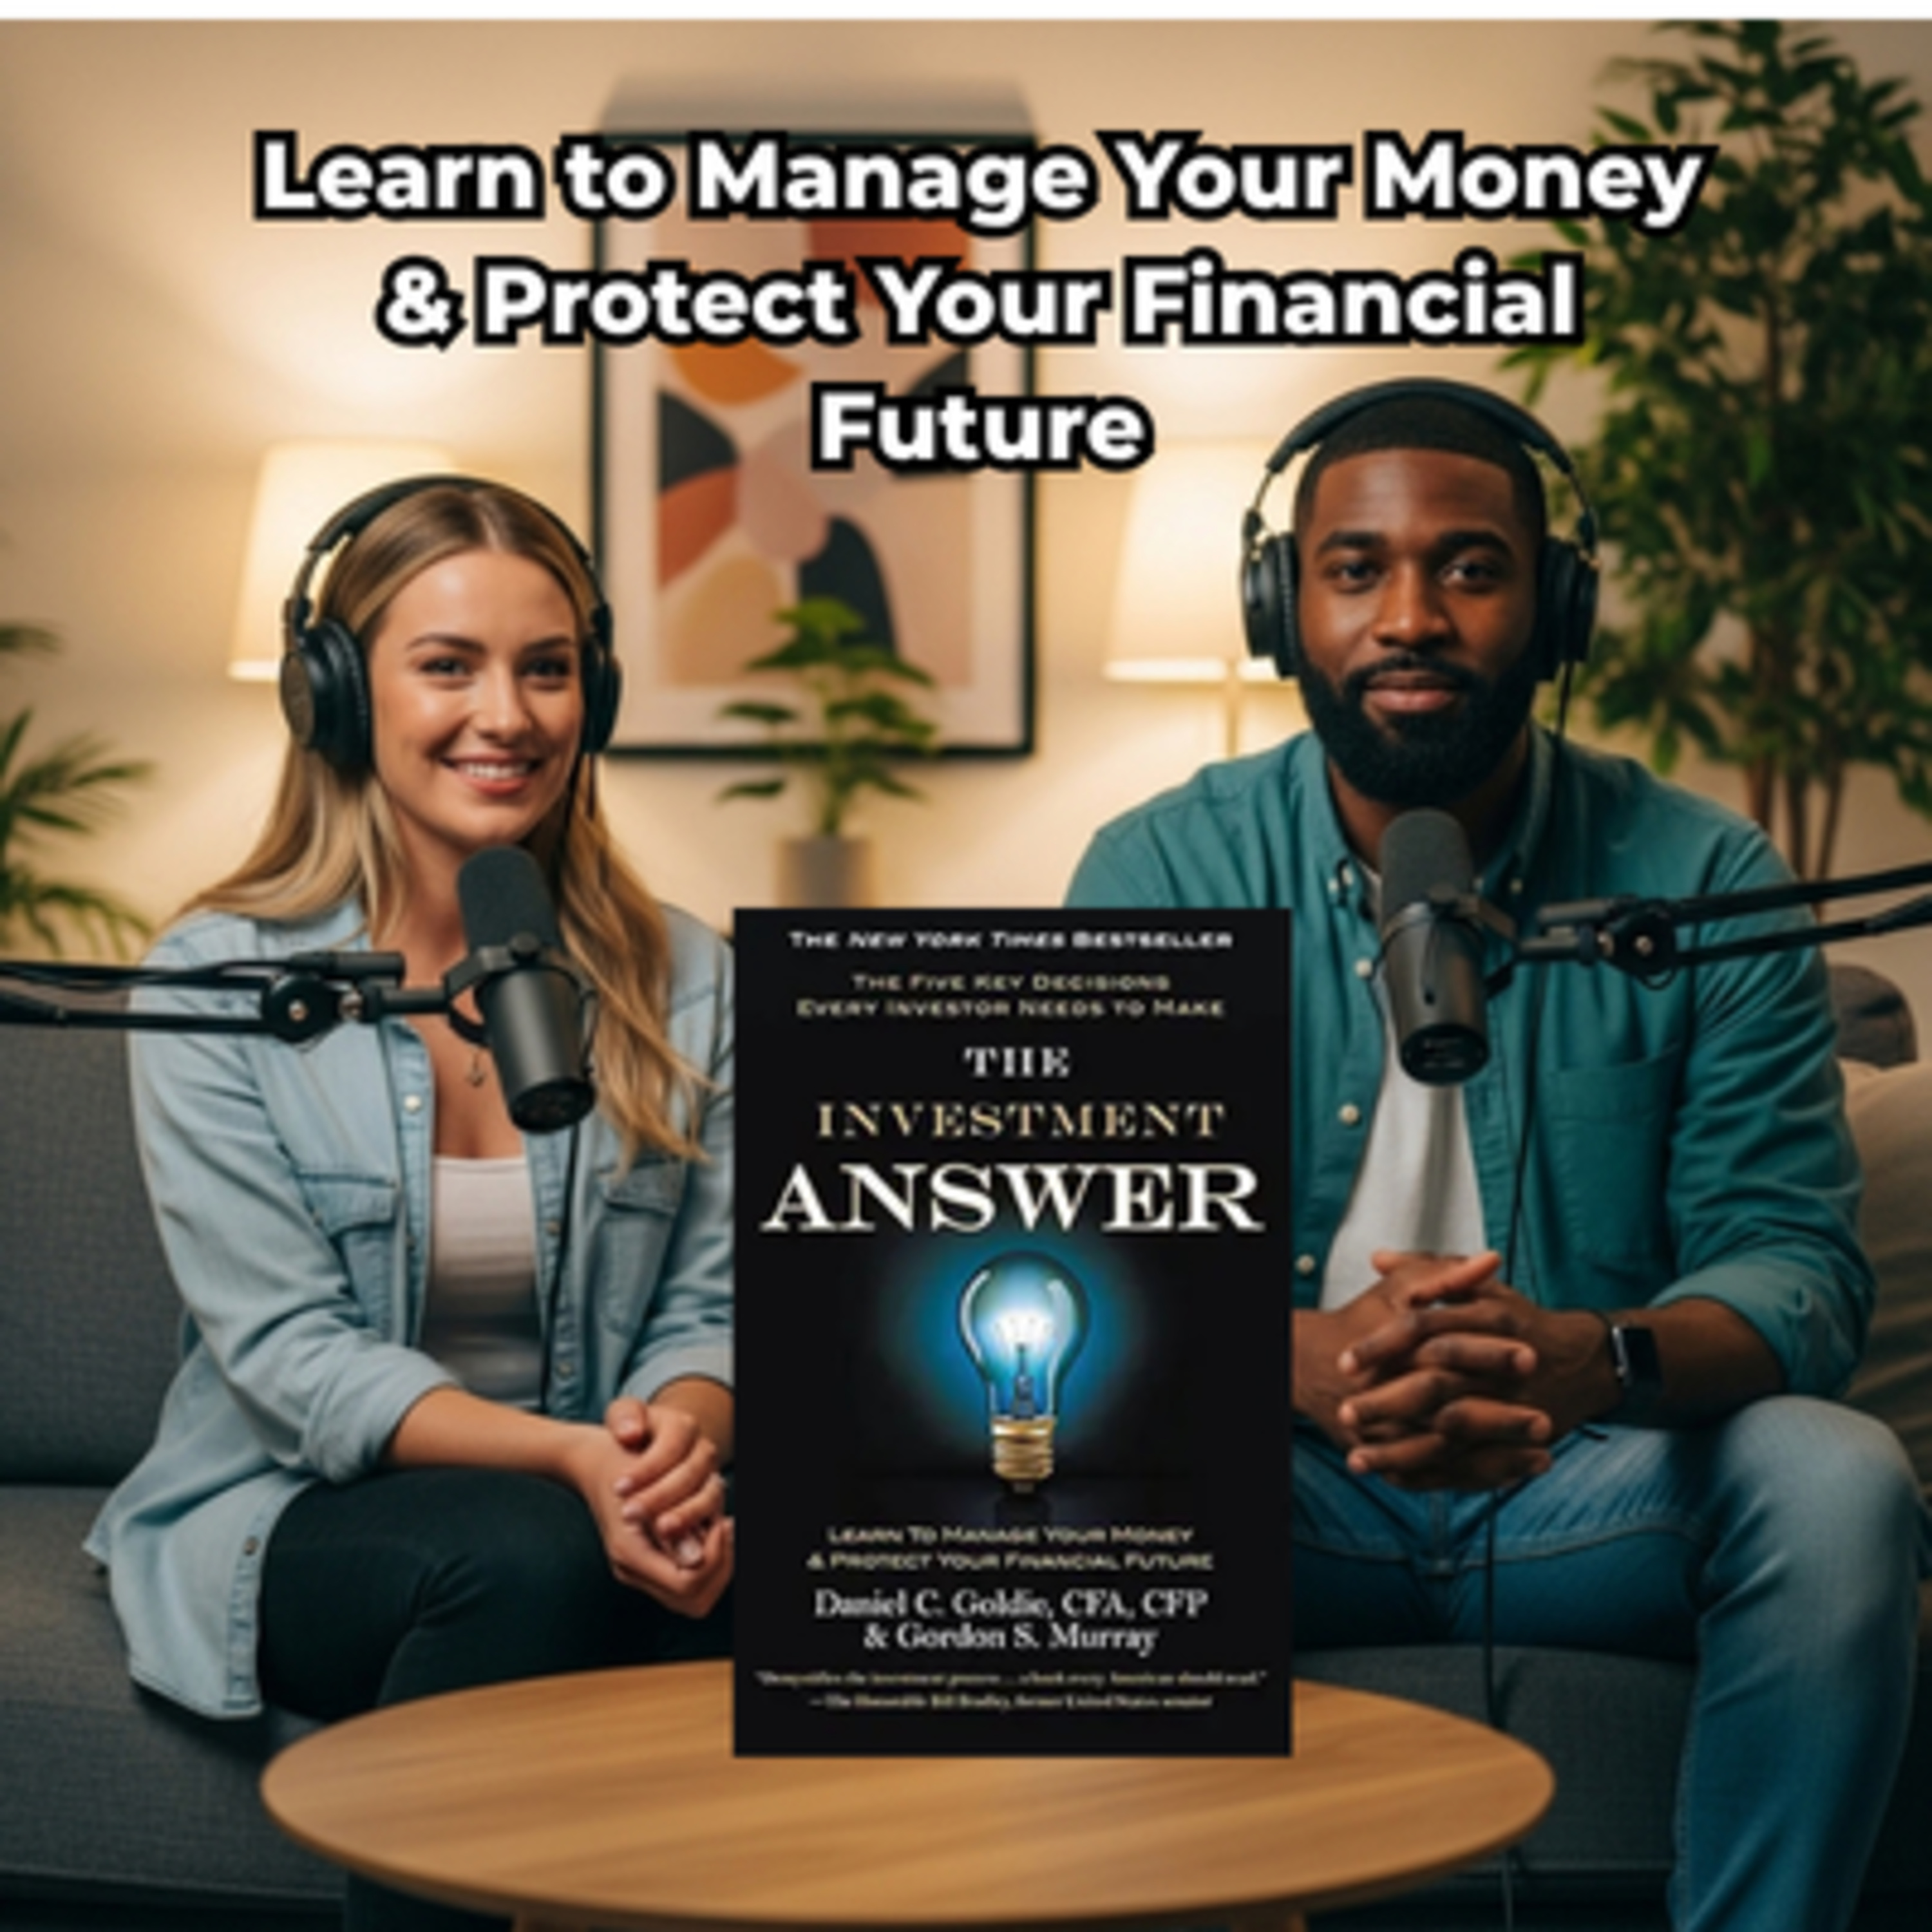
What if there were a way to cut through all the financial mumbo-jumbo? Wouldn't it be great if someone could really explain to us-in plain and simple English-the basics we must know about investing in order to insure our financial freedom?
At last, here's good news.
Jargon-free and written for all investors-experienced, beginner, and everyone in between-The Investment Answer distills the process into just five decisions-five straightforward choices that can lead to safe and sound ways to manage your money.
When Wall Street veteran Gordon Murray told his good friend and financial advisor, Dan Goldie, that he had only six months to live, Dan responded, "Do you want to write that book you've always wanted to do?" The result is this eminently valuable primer which can be read and understood in one sitting, and has advice that benefits you, not Wall Street and the rest of the traditional financial services industry.
The Investment Answer asks readers to make five basic but key decisions to stack the investment odds in their favor. The advice is simple, easy-to-follow, and effective, and can lead to a more profitable portfolio for every investor. Specifically:
Should I invest on my own or seek help from an investment professional?
How should I allocate my investments among stocks, bonds, and cash?
Which specific asset classes within these broad categories should I include in my portfolio?
Should I take an actively managed approach to investing, or follow a passive alternative?
When should I sell assets and when should I buy more?
In a world of fast-talking traders who believe that they can game the system and a market characterized by instability, this extraordinary and timely book offers guidance every investor should have.This episode outlines essential strategies for achieving financial independence by simplifying complex investment principles into manageable actions. It emphasizes the importance of asset allocation, which involves balancing high-risk stocks with stable bonds to align with an individual's risk tolerance. The author highlights diversification and periodic rebalancing as critical tools for maintaining a steady portfolio and protecting against market volatility. Furthermore, the source compares active and passive investing, suggesting that while active trading requires more effort, passive strategies often provide more consistent long-term results. Ultimately, the text encourages investors to critically evaluate performance against benchmarks to ensure informed and strategic financial growth.
#productivityhacks #personaldevelopment #successstrategies #businessinsights #leadershipskills #leadership #ambitiousprofessionals #businesstips #self help #scaling business #businesstactics #professionaldevelopment #startupgrowth #entrepreneurship #businessmindset #growthstrategies
You know, I think everyone has had that moment looking at the just the sheer number of options for stocks and funds, and you realize the biggest hurdle to investing isn't really the complex math. It's that overwhelming paradox of choice. I mean, where do you even begin to build a plan? It's such a common barrier. And investment professionals, well, they often make the market sound like this complex, almost esoteric science, and that just pushes people away. But the core lessons, and we're distilling them here from Gordon Murray and Daniel Goldie's book, The Investment Answer.
They're actually surprisingly few and, you know, surprisingly straightforward. That's the real gift of this material. I think we're about to do a deep dive into a guide written by authors who admit they spent years, you know, feeling intimidated by this whole process. So our mission today is to cut through all that jargon. We want to give you 5 essential high impact tools, not just definitions that you can immediately use. The idea is to build a robust financial foundation and really pursue financial independence with a with confidence.
Yeah. Think of these as the absolute non negotiables. If you only implement 5 disciplines in your financial life, these are the ones. They structure your success and they manage your risk. OK, let's unpack this and start with the foundation Lesson 1. We're beginning with the big strategic decision of understanding asset allocation. Allocation. This defines the entire balancing act between risk and reward. We can use the simple analogy the book suggests, which I love. Just imagine a seesaw at the park.
OK. So on one side you have your equities or stocks. These are the high risk assets, right? They carry the potential for huge returns, but also, you know, big losses and. On the other side, you've got bonds and cash equivalents, much safer. They're designed to preserve your capital, but the trade off is they typically provide lower returns. So allocation is really about deciding the fundamental stability of your entire portfolio. You're deciding, based on your timeline, what percentage of your money you can realistically afford to expose to that volatility and still sleep at night.
Exactly, And the practical challenge is figuring out your ideal balance. For a younger investor, someone who has decades before they'll need the capital, the advice is often to be heavily weighted toward equities because you have the time horizon to write out multiple market downturns. But on the other hand, if you're retiring and say, five years, that balance shifts dramatically. He needs stability. Right. We often hear that rough 100 minus your age rule to get a starting point for stocks. So if you're 40, you might aim for 60% in equities.
Now that rule is, I mean, it's way too simplistic. It doesn't account for your personal situation, but it does provide a necessary starting point for defining your risk. And what's so fascinating about the bond side of that seesaw is that it's not just one thing. Even within that safe category, you're making risk calculations. Oh, absolutely. We just say bonds, but there's a world of difference between, say, super stable government treasury bonds and higher yielding but riskier corporate bonds. And that's the kind of technical nuance that separates a basic investor from an informed 1.
Allocation is your primary safety net. By defining that balanced mix, you really reduce the overall portfolio risk. If one investment fails, the others can prosper and, you know, absorb that loss. The classic scenario they share is so effective. Imagine you went all in on one hot tech stock. Everything's wonderful until that company faces some huge, unpredictable legal problem and the stock price just collapses. Your entire portfolio takes an enormous hit. But if your capital was correctly allocated, meaning it was spread between that volatile stock, some safer bonds and maybe even some real estate, the losses are cushioned.
The other assets in your balance portfolio can absorb that shock. Allocation is the macro strategy. It's about defining your risk exposure. OK. So once you've set that macro balance, your overall split, the next step is protecting that strategy with some micro variety. And that brings us to Lesson 2, accepting diversification. Right. So if allocation is the macro split between asset classes, diversification is the micro distribution of assets within those classes. It's all about preventing concentration risk.
Exactly. I love the analogy they use here. It's like a fruit basket at the grocery store. If you allocate 60% of your money to the fruit class, which is equities, diversification means you don't spend that 60% only on apples. Right. You need bananas, oranges, berries. Different colors, different sizes. Yeah, and the implementation is simple, but it's really profound. You divide your investments across a wide variety of different industries, sectors, even geographic regions. So that's 60%. Stock allocation shouldn't just be domestic tech stocks.
It should include things like consumer staples, utilities, healthcare, and maybe even some foreign investments or emerging markets. And the stability advantage you get from that variety is just huge. It's because of correlation, or I guess the lack of it. When one sector, let's say domestic tech, takes a massive dip because of new regulations, another sector like foreign consumer goods or stable utility bonds might rise or at least hold steady. That offsetting action is the whole point. It's not about finding the next big winner, it's about making sure the next big loser doesn't wipe out all your returns.
Diversification helps ensure that the overall roller coaster ride of your portfolio has, well, far fewer sickening drops. And the source makes this point so clearly, if a major well known business plummets because of bad news, your losses are just so much less painful if you've also invested in unrelated sectors, things like inflation resistant real estate or short term corporate bonds. Diversifications often called the only free lunch in investing, and that's because it lowers your volatility without necessarily having to reduce your expected returns.
So we've established the structure, we filled the basket, now we move on to Lesson 3. And this is about the commitment needed, needed to manage it all, active versus passive investing. Yeah, this is a big strategic choice. It's about how much time, energy, and frankly, money you want dedicated to managing your portfolio. You can look at it as choosing one of two walking routes. The active route is congested, full of detours and it requires constant attention. Active investing. It involves trading frequently, trying to time the market, picking specific stocks or using those actively managed mutual funds with the explicit goal of beating the market index year after year.
Which means you've got to be constantly studying, observing, analyzing, and while it can lead to higher returns, it just inherently carries higher risk and much greater expense. Oh, the expense is key. Those trading fees and the elevated expense ratios of managed funds really add up. And that's a key technical take away for any informed investor, right? Those costs matter immensely. They really do. Actively managed funds can charge expense ratios of 1.2% or even more every year over a 20 or 30 year period.
Those fees, they compound, they can strip thousands and thousands from your overall returns. And you compare that to the calm, easy to follow passive route. This is just buying and holding assets like index funds that track the broader market, like the S&P 500. You're not trying to beat the market, you're just trying to beat the market. The passive approach is just a less formal, less stressful method. It takes minimal time and energy, but most importantly it offers incredibly low costs. These low cost ETS exchange traded funds can have expense ratios well under .1%.
They're also generally more tax efficient because they don't trade as often. The source makes a really powerful case for the passive route and it highlights the reduction in stress levels and I get that Peace of Mind. But here's my question. Does the book suggest any scenario where the effort and stress of active investing is actually justified for, you know, a regular individual investor? They're brutally honest about it. They say that while some highly skilled professional traders, people who dedicate their entire lives to it, might beat the market, the vast majority of individual investors and even most professional fund managers failed to outperform their benchmark once you factor in the fees, especially over the long term.
So the lesson isn't that active investing is impossible, it's more that unless you're ready to make a huge financial and intellectual commitment to research and high fees, passive investing is just the statistically and psychologically superior choice for building long term wealth. Absolutely. It lets you step away from the daily screen volatility while your investments just compound steadily, knowing that the market historically rises over time. OK, so you've set your macro allocation, you've diversified your micro holdings and you've chosen your passive route.
But you can't just walk away forever. Market shifts require a period periodic reset, and that moves us right into Lesson 4, regularly rebalancing. This is the mechanical necessity of portfolio maintenance. Let's go back to that balancing scale analogy. You set your scale perfectly at your target. Let's say it's 60% stocks, 40% bonds. But over time, the market moves things around. Your stocks might do so well that they push your portfolio to an unintentional and much riskier 7030 split. So we've accidentally drifted into a much higher risk tolerance than we originally signed up for rebalancing.
Is that necessary periodic adjustment? Exactly. You have to move your portfolio back toward your goal allocation, maybe once a year. And this involves selling some of the assets that have done really well, locking in those profits and then reinvesting those proceeds into the assets that have been lagging. This is the point where investors often feel a really strong psychological resistance. It feels, I mean it feels inherently wrong to sell a winner and buy something that's been flat or even falling.
But this is where it gets really interesting and why it's such a fundamental discipline. When you sell the asset that's currently expensive to buy the asset that's relatively cheap, you're basically forcing yourself to follow that timeless mantra of buy low, sell high. The advantage is twofold. First, it manages your risk, keeping you strictly aligned with your original comfort level no matter what the market hype is saying. And 2nd, and this is crucial, by forcing yourself to transfer profits into those cheaper, lagging assets, you position yourself to maximize returns when those underperforming sectors eventually recover.
It's a systemized, unemotional way to maintain control. Yeah, think of that classic example. The author shared an investor who made big investments in a certain sector during a market peak. A year later, those stocks have surged so much they now account for 80% of the investors total capital. That investor is sitting on a massive potential risk bomb. If that single sector faces an inevitable cyclical downturn, they could sustain crippling losses. Rebalancing enforces the necessary discipline. You sell a portion of that highly appreciated stock and move the money into bonds or other conservative investments.
You're preparing the portfolio for the inevitable cycle shift. That concept of preparation, in comparison, brings us to our final and maybe the most critical lesson. It's an evaluative tool. Lesson 5. Wisely seeking context or just asking the crucial question. Compared to what? This is a lesson in critical perspective. We have to evaluate investments performance relative to an appropriate objective benchmark, not just an isolation. You can't just look at one number and feel good about it. It's like overhearing your friend boasting about a great stock they just bought that returned 10%.
You have to immediately ask them. OK, but compared to what? Exactly. If the overall market index or comparable mutual fund returned to 18% during that same time frame, then your friend's great sock actually, you know, significantly underperformed the average opportunity that was available. So when you're looking at a specific tech stock, you shouldn't just look at its return. You have to assess how it performs against a tech mutual fund or a broader tech index. That context, that comparison, clarifies whether you're making a truly wise purchase or if you're just riding a temporary market fad that every other investment in that sector is riding even harder.
Without context, enthusiasm can just be ignorance. The source illustrates this perfectly. An investor was overjoyed because their trendy tech company had done really well, only to later learn that a more established similar company had severely outperformed their investment during the exact same period. If that investor had just asked that crucial question, compared to what? Against the right benchmark, they would have realized they weren't maximizing their opportunity. It would have led to a better, more informed choice.
And that, you know, ultimately is the framework. Investing is about achieving stability and financial freedom, not just gaining more money. By following these five key guidelines, allocation, diversification, strategy, rebalancing, and contextualizing performance, you lay the structural foundation for a truly profitable life. These aren't just market tips, they're structural disciplines. They ensure you stop reacting to the market and start maintaining control over your risk, staying aligned with your long term goals.
And if we take that final lesson, compared to what? And apply just one step further, if we know that investments have to be judged against an objective, relevant benchmark, what other aspects of our financial lives are are we failing to judge effectively? Wow. Yeah, We're talking about everything from our weekly spending habits to our current debt management strategy. Are we comparing our current savings rate to the average for a demographic or are we comparing it to the actual rate we need to hit our retirement target?
That's the ultimate challenge. Most of us just accept the financial status quo, our level of debt, our emergency fund size, without ever defining A realistic, challenging and effective benchmark, a benchmark against which we should be comparing our entire financial strategy. Defining that comparison point is the essential next step in achieving true, comprehensive financial literacy, something powerful for you to chew on until our next deep dive.
 Apple Podcasts
 Castbox
 Castro
 Goodpods
 Moon FM
 Overcast
 Pocket Casts
 Podbean
 Podcast Addict
 Podcast Republic
 Spotify