Financial Feminist: Overcome the Patriarchy’s Bullsh*t to Master Your Money and Build a Life You Love―A Personal Finance Handbook for Women, Mindful Spending, and Financial Literacy
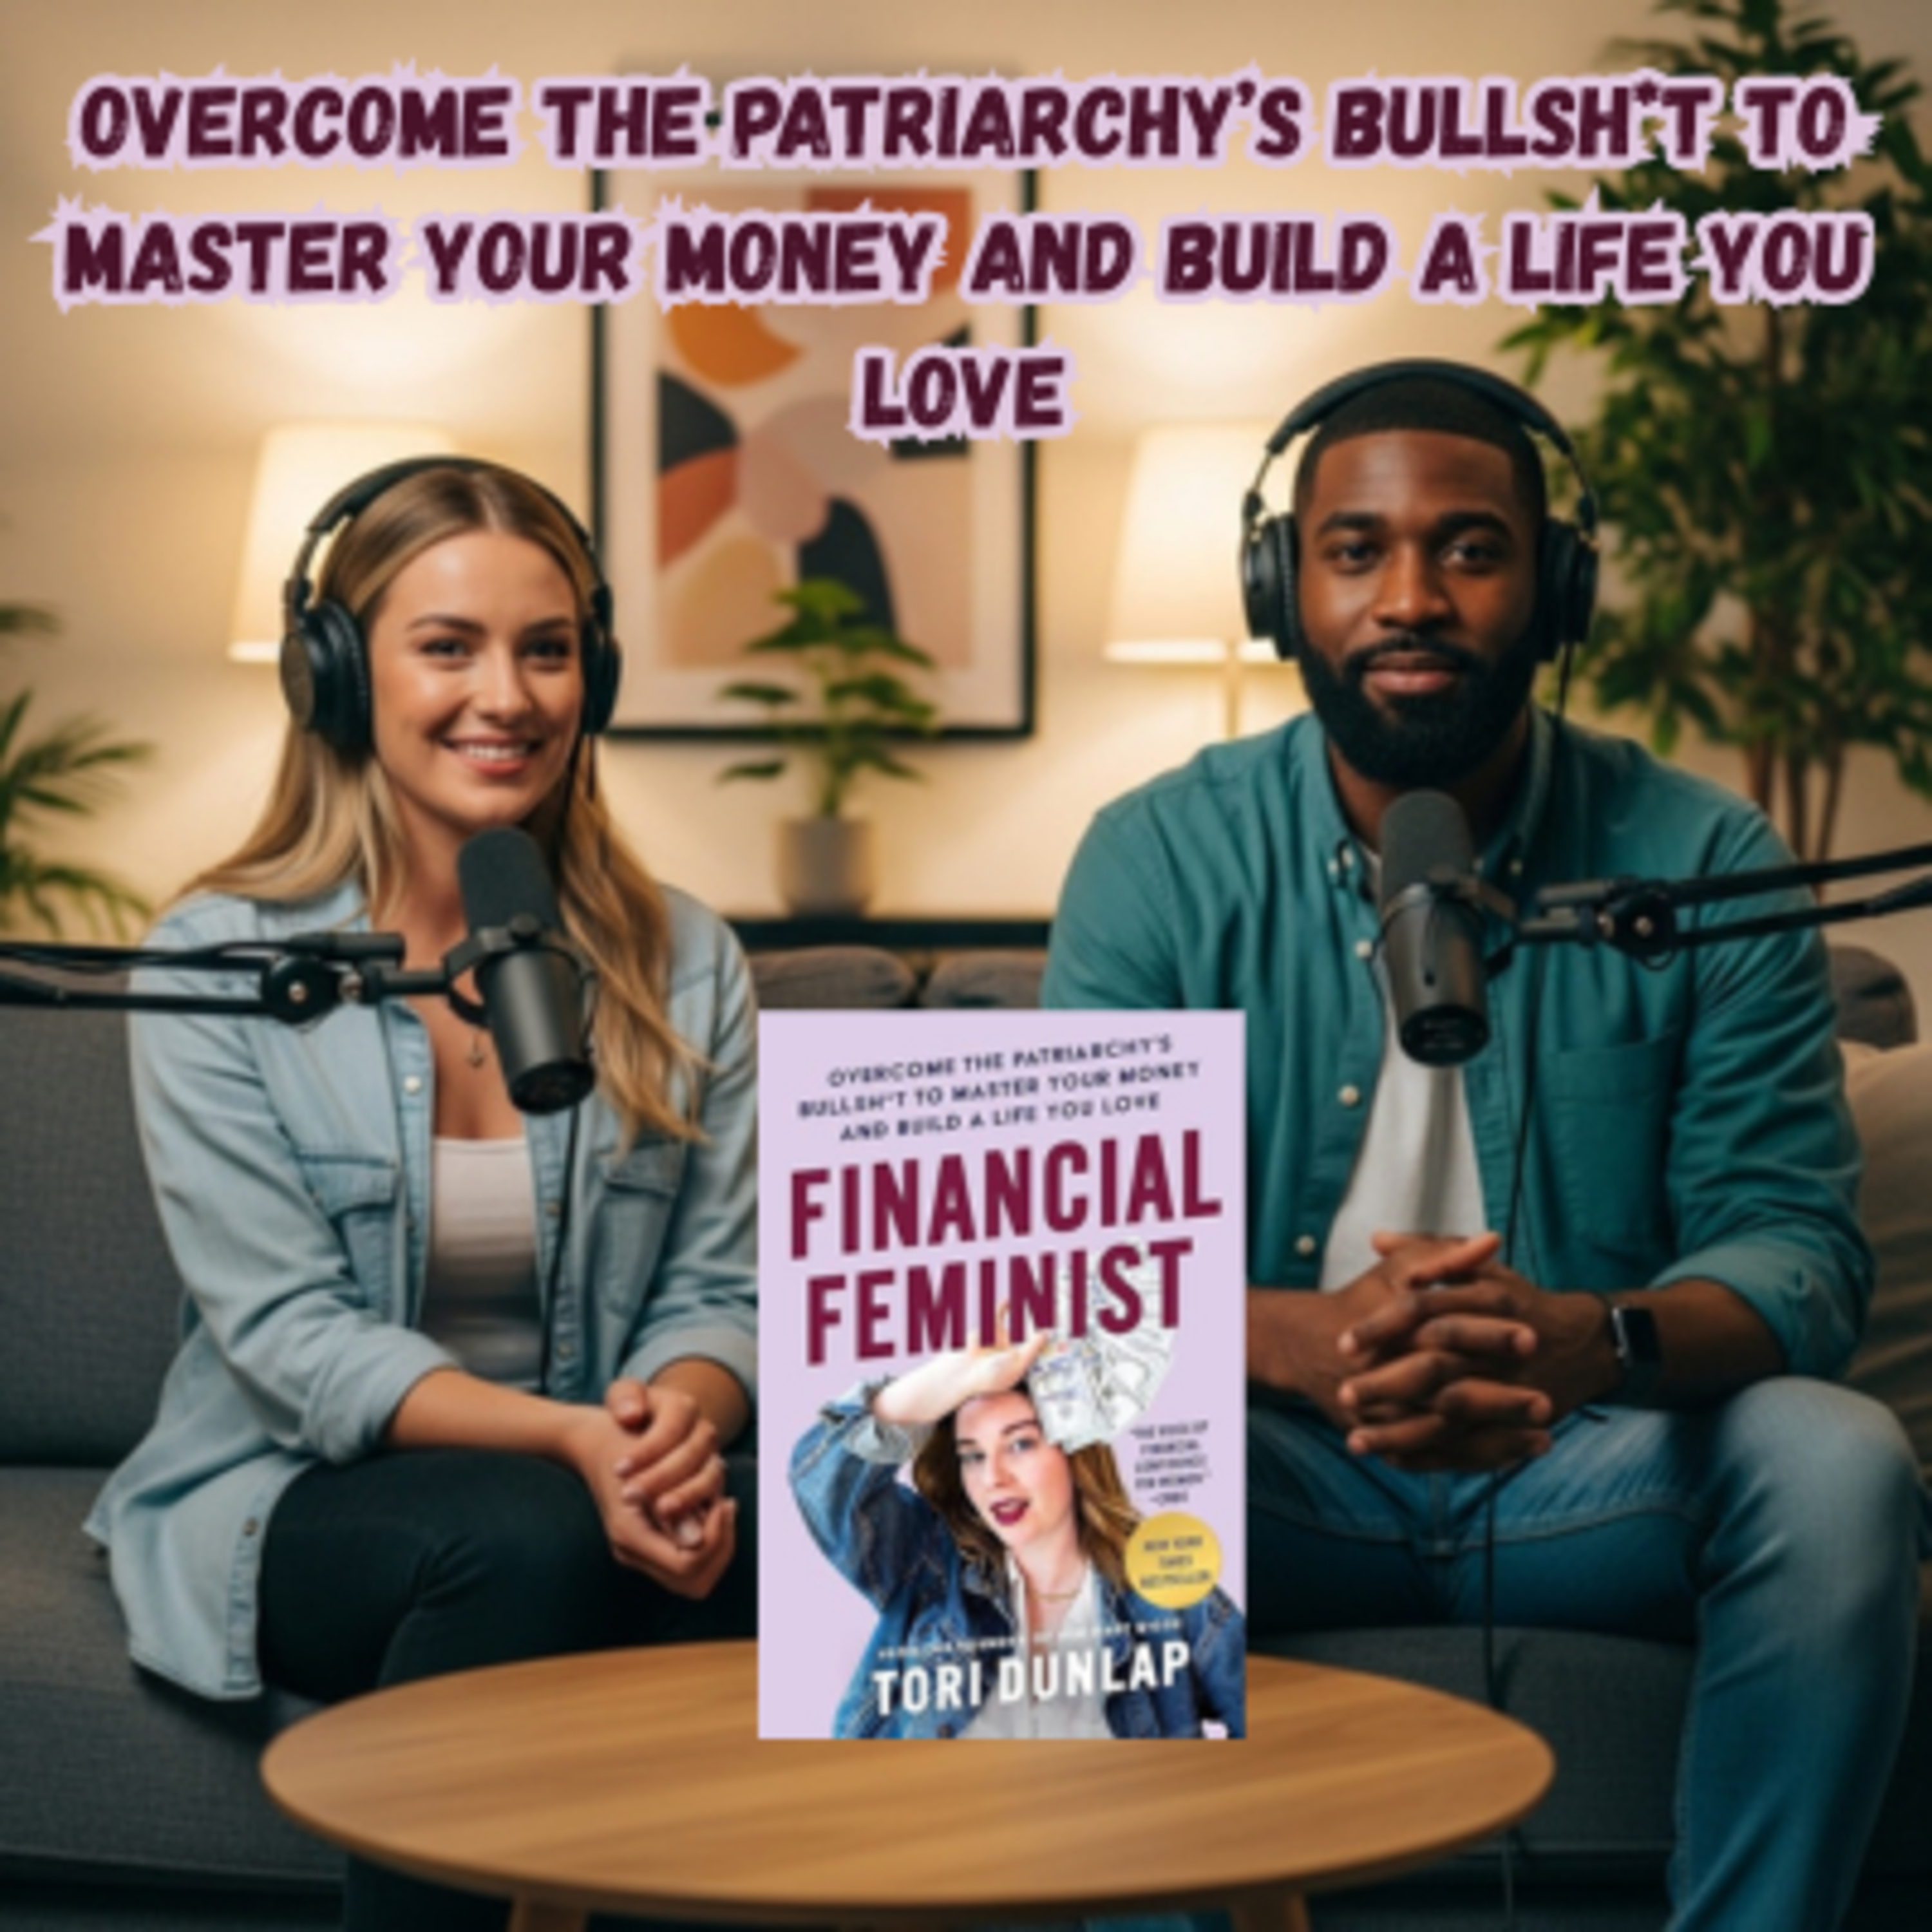
Money isn’t just math—it’s power. In Financial Feminist, globally recognized finance educator and founder of Her First $100K, Tori Dunlap, redefines what it means for women to take control of their finances in a system built to hold them back.
In this episode, we unpack Tori’s unapologetic approach to earning, saving, investing, and spending mindfully—without shame, guilt, or restriction. You’ll learn how to overcome money anxiety, negotiate your worth, build generational wealth, and align your financial choices with your values. This isn’t about budgeting to survive; it’s about using money as a tool for freedom and impact.
Because when women master their money, they don’t just change their lives—they change the world.
If this episode made you rethink your relationship with money, follow BookTunez for more empowering and practical financial wisdom every week. 🎧
Share this with a woman who deserves to feel confident about her money—and remind her that financial independence is a feminist act.
Because true equality begins with economic freedom.#FinancialFeminist #ToriDunlap #BookTunez #HerFirst100K #WomenAndMoney #FinancialFreedom #MoneyMindset #InvestingForWomen #FinancialLiteracy #Equality #EmpoweredWomen #MindfulSpending
All right, so we're diving deep into financial feminists today. Yeah, getting into the nitty gritty of Tori Dunlap's advice. Exactly. We're pulling out those super practical takeaways. Adding in some extra expert insights along the way of course of. Course, And you know what I love about this book is how approachable it is. Oh, absolutely. It's not just for finance gurus. Right, It feels like Dunlap is like chatting with you, like a friend giving you advice over coffee. Totally agree, and she really gets that money isn't just about numbers.
No, not at all. It's about emotions. It's about our mindset. That's actually her first big lesson, right? It is dealing with all those feelings that come up around money. Fear, guilt, shame. We've all been there, haven't we? Absolutely. I think Dunlap really nails it when she talks about how these emotions can sabotage our best intentions. Remember Sarah story from the book? Oh, Sarah. Yeah, she was just paralyzed by anxiety every time she tried to budget. Exactly. And you know, it's so common, but Dunlapf suggestion to journal about those feelings.
That was brilliant. Wasn't it? Sarah realized her anxiety actually stemmed from her upbringing, not her current finances. And that's such a powerful realization, isn't it? Just acknowledging those emotional roadblocks can be huge. It's like Step 1 to overcoming them. And then you can start making decisions from a more rational place, not driven by fear or guilt. OK, so once you've tackled those emotional hurdles, Dunlap dives into intentional spending. Lesson 2. I love how she reframes budgeting.
Me too. It's not about deprivation, it's about making sure you're spending aligns with your values. Absolutely. She wants you to ask yourself, does this purchase really reflect what's important to me? That's. Such a good question to ask and you know what example comes to mind? Oh. Let me guess, Emily in the coffee addiction? Yes, instead of telling Emily to cut out her lattes completely, what does Dunlap suggest she. Tells her to invest in a quality coffee maker. Genius. So Emily still gets her caffeine fix.
But in a way that actually aligns with her goal of saving for travel. It's a win win. I mean if I ever had any Emily moments like that. Something you spent way too much on but could re evaluate. Oh, definitely. We all have our little splurges. Yeah, but Dunlap's point is to be mindful, right? Make sure those splurges fit into the bigger picture. Absolutely, and that sense of control, it can be really motivating as you move on to Dunlap's next lesson, building a financial game plan. Right. So this is where we start thinking long term.
Exactly what are your goals? Where do you want to be financially? And Dunlap emphasizes that you don't need to be a spreadsheet wizard to figure this out, no. Thank goodness she uses Tom's story. Remember, he was terrified of building an emergency fund. It just felt so overwhelming. Yeah, but instead of giving up, he broke it down into smaller steps. Yeah, like saving $5000 in a year. Which seemed way less daunting when divided into monthly contribution. So smart. It is. It's about those small wins, like a fitness challenge where you start with 10 minutes a day and before you know it, you've hit your target.
And you know what I loved about Tom's story? Those small wins gave him the confidence to tackle even bigger goals. That's so important. That sense of accomplishment keeps you going. It's like this positive feedback loop. Small wins lead to bigger wins. OK, now for lesson 4. This one could be a bit tougher to talk about effective debt management. Yeah, debt can be such a loaded topic. Right, but I love how Dunlap normalizes the experience. Like it's OK if you're in debt. It doesn't define you. It's a challenge, but you can overcome it.
Yeah. She uses David's story here. Right. Dealing with student loan and credit card debt. And instead of feeling totally stuck, David focuses on tackling the highest interest debt first. Which is the essence of the snowball method. Right, exactly. Pay off the smaller debts first. Get that momentum going. And it's not just about the math, it's about that psychological boost, seeing the balances shrink, even if it's just a little bit at first. Oh, for sure. It keeps you motivated. OK, Are you ready for the final lesson?
Hit me with it. Investing to build wealth. Dunlap just throws out the myth that investing is only for the rich. Love that she empowers you to take control no matter how much money you have to start with. Absolutely. And she has some great tips for beginners, but we'll get into those in the next part of our deep dive. Can't wait. All right, welcome back to our deep dive into financial feminist. So in Part 1 we went through Tori Dunlap's 5 core lessons, right? Yep, those big takeaways for achieving financial well-being.
But you know no single book can give you like A1 size fits all solution. Right. Definitely not. And that's where some some nuances, maybe some critiques come in. Yeah, like one thing that stands out is how Dunlap really focuses on, like, young, professional women. Right, and her examples, they might not resonate with everyone. Like, remember Emily and her latte habit? Yeah, someone's struggling to make ends meet might not relate to that. Exactly. And Dunlap does acknowledge those limitations. She wants readers to adapt her advice.
You know, make it work for their own situation. Yeah, it's about figuring out what makes sense for you. Like, investing is great for building wealth, but maybe not if you're facing immediate financial hardship. Right. Got to prioritize those basic needs 1st and then you can layer in those long term strategies as things improve. Makes sense? But even within her target audience, some people say like her focus on individual empowerment and it kind of downplays bigger issues like the gender pay gap.
That's a good point, but I think Dunlap tries to find a balance. You know she pushes for both personal responsibility and systemic change. So it's about working within the system, but also pushing for broader reforms. OK, so let's circle back to something practical. We talked about intentional spending, but how does that translate into like an actual budget, one that really works for you? Well, there are tons of budgeting methods out there, but let's stick with 1. Dunlap mentions the 5030 Twenty rule.
It's a pretty simple framework. OK, break that down for me. Simple is good when it comes to budgeting. Basically you aim to spend 50% of your income on needs, 30% on wants and then 20% goes to savings and debt repayment. OK, so not about restricting yourself completely, more about finding a balance, right? Yeah, enjoy life, but also, you know, work towards your financial goals. And Speaking of goals, remember how Dunlap encourages us to start investing early. Yeah, she's all about those index funds and ETFs for beginners, right?
Exactly. Now we mentioned ETFs earlier. Want me to explain why they're a good starting point for new investors? Yes please. I'm still a bit fuzzy on those. OK, so think of an ETF like a basket of stocks. It tracks a specific market index, like the S&P 5. 100 Oh, OK. So instead of picking individual stocks, you're spreading your risk across a whole bunch of companies. Exactly. Instant diversification. But Dunlap is also clear that you got to do your research before jumping in. Makes sense? Understand what you're investing in.
Make sure it aligns with your goals and your risk tolerance. Right, don't just blindly follow anyone's advice, even if they call themselves a financial guru. Now let's go back to debt management for a second. We talked about the snowball method, which Dunlap loves. Yeah, paying off the smaller debts first to get the momentum going. But is that always the best strategy? Good question. Is there a better way? Well, while the snowball method can be super motivating, it might not always be the most financially efficient.
OK, how so? Sometimes tackling the high interest debt first makes more sense mathematically, even if the balance is larger. So it's a trade off like quick wins versus minimizing interest payments in the long run. Exactly. And that's where talking to a financial advisor can be helpful. They can look at your specific situation, help you make a plan. Yeah, like a personal trainer, but for your finances. OK, shifting gears a bit, what about Dunlap's emphasis on financial independence and building wealth?
Some people say that kind of thinking can be too individualistic. You know, like it ignores the need for a collective solutions to economic inequality. Yeah, it's definitely a complex issue. It's important to acknowledge those systemic barriers, right? Not everyone has the same opportunities so. It's not just about individual effort. Right, it's about creating a more level playing field where everyone has a fair shot at financial well-being. And that benefits society as a whole. OK, so we've talked about some nuances and critiques of Dunlap's approach.
What are the key takeaways for a listener like as they continue their financial feminist journey? Well, first and foremost, remember that personal finance is personal. What works for one person might not work for another. Yeah, got to find what resonates with you. Exactly. Experiment, adapt the advice to your own situation, and don't be afraid to ask for help along the way. Right, There are so many resources out there, financial advisors, online communities, even just talking to a friend or family member you trust.
And maybe most importantly, be patient with yourself. Financial literacy is a journey. It's OK to make mistakes. Yeah, progress over perfection. Now I'm curious what's been resonating with our listeners so far. All right, so we're wrapping up our deep dive into financial feminists. We've covered so much ground from those five key lessons to, you know, some alternative viewpoints and critiques. And now it's your turn. We want to hear what's been resonating with you throughout this whole deep dive.
Yeah. What's got you thinking? Maybe you're ready to try that fifty 3020 budget. Or maybe you're finally ready to start investing. You know those index funds we talked about? Or hey, maybe you're feeling a little overwhelmed. Like where do I even start? Totally understandable. Remember, this is a journey, not a race, and sometimes that first step, you know it's the hardest. It is getting over those initial doubts and fears and you know, something that comes up a lot is how to deal with those curveballs life throws at you.
Right, those unexpected things that can totally derail your plans. Like Dunlap says, stuff happens. Yeah, job loss, medical emergencies, who knows? Things we can't always predict or control. And while we can't eliminate risk entirely, we can build in some resilience. That's where that emergency fund comes in. That's why Dunlap is so big on saving, even if it's just a little bit at a time. It's your safety net like a cushion when things get rough. Helps you weather those storms without totally derailing your long term goals.
Speaking of goals, let's go back to financial independence for a minute. What does that actually mean to you? Yeah. Is it early retirement, starting a business, or just, you know, having the freedom to make choices without stressing about money? It's different for everyone, but the main idea is having control over your finances, right? Having the power to shape your own life. Exactly. But you know, this brings up a bigger question, like, how does personal finance fit into a world with so much economic inequality?
Yeah, some people say focusing on individual responsibility ignores those systemic barriers that hold so many people back. It's a valid point. We can't just pretend those barriers don't exist, but I do believe that like personal finance, can be both empowering for individuals and a force for social change. Gunlab talks about that too, right? She wants readers to manage their own money well and also advocate for policies that promote economic justice. Yeah, it's about combining personal responsibility with collective action.
That's how we create a more equitable society where everyone has a chance to thrive. Absolutely. So as we wrap up our financial feminist deep dive, remember this. Financial literacy is a journey. You learn as you go, You try things out. You adjust your approach as your life changes. And most importantly, don't let fear hold you back. Embrace the power of personal finance. Use it to build a life that's both financially secure and, you know, deeply fulfilling. Couldn't have said it better myself. Thanks for joining us on this deep dive everyone.
Hope you walked away with some valuable insights and tools to help you on your own financial journey. Remember, it's not just about the money, it's about creating a life you love.
 Apple Podcasts
 Castbox
 Castro
 Goodpods
 Moon FM
 Overcast
 Pocket Casts
 Podbean
 Podcast Addict
 Podcast Republic
 Spotify